အကူအညီ / ဝင်ရောက်ခွင့်နှင့် ထိန်းချုပ်မှု
ဤစာမျက်နှာကို မဘာသာပြန်ရသေးပါ — အင်္ဂလိပ်စာသားကို ပြထားသည်။
The “Control” section
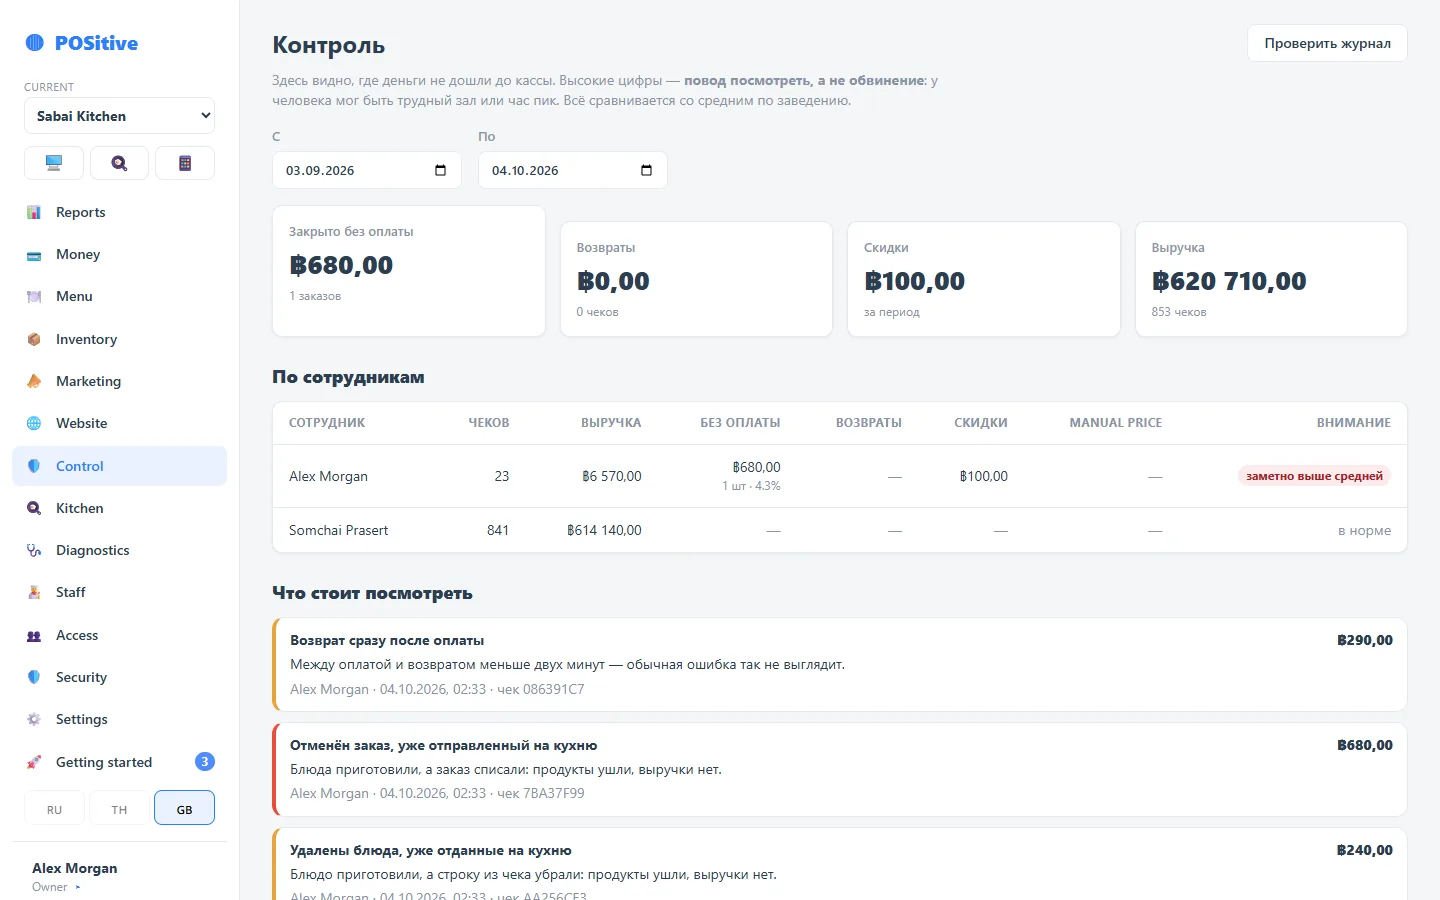
Voids after the kitchen, discounts, manual prices, closings without payment, abandoned orders and red flags.
The section gathers what usually gets lost between receipts: actions that look normal one by one but add up to a picture together.
What to look at
| What | Why it matters |
|---|---|
| Voids after the kitchen | The dish has already been cooked — a direct loss. You see who and for how much |
| Discounts | Especially manual ones: who, how much, on which receipts |
| Manual prices | Items whose price was set by hand |
| Closings without payment | On-the-house items and written-off receipts with a reason |
| Refunds | Who, what, when and why |
| Abandoned orders | Entered, cooked — and never closed |
Red flags
The system highlights the unusual: many voids by one employee, regular shift discrepancies, discounts above the usual. This is not an accusation but a reason to look more closely.
How to investigate
- Open a period — usually a week or a month.
- Look at the totals: voids, discounts, closings without payment.
- Find who they concentrate around.
- Open the specific receipts and the event log — the sequence of actions is visible there.
- Talk to the person with the receipt and the time in hand, not a feeling.
Most often it is not theft
In the first months most “red” figures are learning: the cashier does not know how to void an item properly and does it the way they can. Investigating is necessary, but the conversation is better started with a question than an accusation.